The Blog
Long-form on the decisions behind the startups, operators, and capital shaping East Africa — every claim sourced.

What to tell a candidate when the company is struggling
Nine months of runway and a round that has not closed. Say nothing and you hire someone who would have said no. Say it badly and you hire nobody. There…

Two teams both think they own it
Sales says onboarding is product's job, product says it is a service problem, and the customer has been waiting nine days. Nobody is shirking. The arrangement is doing exactly what…

The supplier is cheap because of something
They are thirty percent below anyone else and they have missed three deliveries. Before you decide whether they are failing, work out what the price was buying and which of…
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
The roadmap promise you made in a meeting
You said it would probably be ready by Q3. They wrote it down as a commitment, told their own stakeholders, and you have now sold something twice: to them, and…

The regulator has asked for something you do not have
A letter arrives requiring a control, a record or a licence you cannot produce. The instinct is to answer it well. The first job is to work out whether this…

Hiring someone who knows more than you do
You cannot assess the craft, you cannot supervise the work, and the usual interview measures how well they explain it to someone who would not know. Three things fix most…

The discount is permanent and the case study is not
They will give you a named reference in exchange for twenty percent off. You are trading a price that resets every renewal for proof that decays in eighteen months.

Everyone is at the conference, which is the problem
The stand costs four thousand and a week of the team. The return comes from one or two conversations, and you can find out in advance whether those people are…

Adding an interviewer does not add judgement
Six people now meet every candidate and the process feels rigorous. Most of them are measuring the same thing, one of them has an effective veto, and nobody designed either…
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
Your co-founder and your investor want different things
One wants to raise and go faster, the other wants to reach profitability. Both have arguments. Only one of them has a consent right, and nobody in the room has…

You are going to break a promise. Choose which.
Three commitments, one quarter of capacity. Deciding by which deadline is nearest means the choice gets made by the calendar, and the calendar does not know what any of them…
One customer uses it and you cannot remove it
The feature costs you a day a month and shows up in four percent of accounts. Removing it is judged as a loss, it is holding up workflows you cannot…

Two finalists and no way to tell them apart
You have run four interviews each and the team is split. The gap between them is smaller than the error in your measurement, which means the fifth interview will not…
The hire is failing and you chose them
Month five, the work is not landing, and every option feels like an admission. The signal you are reading is not about them yet, and the thing draining while you…

A non-binding letter still binds you
It commits nobody to anything, which is exactly why signing it costs them nothing and costs you the next four months.
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
They are using it wrong, and that is the finding
A third of your accounts are doing something the product was not designed for. The instinct is to correct them. The information is in why nobody had to be told.

The counter-offer buys you six months
A competitor is hiring your people. Matching the money changes the number and not the reason, and it teaches everyone still here how to get a raise.

An investor who will not lead is not in your round
Thirty meetings, real enthusiasm, no term sheet. Interest costs nothing to express, and a process made of people waiting for someone else to move never converges.

You cannot un-publish the source
Open sourcing a component is discussed as a marketing decision and executed as a permanent one. The licence is forever, the community is three people, and both of those are…

The refresh grant is compared, not valued
You are deciding how much equity to give people two years in. They will not assess the number against what it is worth. They will assess it against their first…

Moving upmarket changes what you are, not just who you sell to
Larger buyers do not evaluate you individually, they sort you into a class. The feedback on whether the move worked arrives two quarters after you have committed to it.
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
Your best engineer wants to manage
Saying yes removes your strongest individual contributor and creates an untested manager. Both halves are costs, and the promotion is usually written so that neither can be undone.
During the outage, you cannot explain it yet
Customers are asking what happened and you do not know. The instinct is to wait until you can answer properly, and the waiting is what costs you.

Advisor equity is permanent and the advice is not
A recognised name for half a percent sounds cheap. The name is a claim that cost them nothing to make, and the shares outlive the relationship by a decade.

Your first salesperson is being asked to invent the job
You are hiring someone to run a sales motion that does not exist yet, and you will measure them as though it did. That structure fails whoever you put in…

You never ran diligence on the investor
They spent six weeks checking you. You checked their website and asked two people who were always going to say something polite.

Exclusivity is a sale of your whole market
They want to be your only partner in the region. Whatever they pay for that is a price on every customer you have not met yet, and the term will…
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
Hiding your price does not make it higher
Contact us protects the number in the deal you are already in. It costs you every buyer who priced you at their guess about your category and never made contact.

A second office doubles the situations, not the capacity
The plan says twice the market for less than twice the cost. What actually doubles is the number of distinguishable things that can go wrong, and your ability to respond…

A competitor copied you, and most of it did not transfer
They shipped your feature set in eleven weeks. What they could copy is what you made visible, and the visible part was never the part that was working.

Your co-founder wants out
The equity conversation feels like the hard part. It is the easy part, and treating it as the whole thing is how founders end up negotiating with a stranger who…

They already know, and they have guessed worse
You are deciding when to tell the team. They have been reading your calendar, your face and who was in which meeting for three weeks, and they have reached a…
The customer who wants it built their way
The contract pays for the build. It does not pay for the queue it jumps, the scope that arrives afterwards, or the share of your roadmap it owns in two…
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
What you pay yourself is a decision, not a sacrifice
A founder salary set too low is not discipline. It is an unpriced exposure on the one person the company cannot replace, and it is read by everyone as information.

The strategic investor is buying something and it is not equity
A corporate cheque on generous terms is not charity and not stupidity. Work out what the terms are paying for before you decide whether you are selling it.

The money is already gone, so stop counting it
Nine months and a budget into a project that has not worked. The only live question is what the next six months buy, and it is the one question nobody…

Your analysis was right and nobody ran it
Being correct is one problem. Being adopted is a different problem with different mechanics, and most good work dies of the second one.

You are negotiating with someone who has no choice
Before you plan the conversation, ask whether the person across from you is choosing or trapped. Almost every wasted negotiation is that question skipped.

The person you cannot replace just resigned
You are about to search for someone like them. The reachable goal is the state they were holding, and that is usually assembled from parts rather than found in a…
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
Less than 20%, and the questions the model got wrong
A Census Bureau story from 26 May 2026 puts firms with four or fewer employees under 20% AI use. Two experiments show what happens on the questions the model got…

Your hiring freeze takes effect two quarters from now
Headcount is a level you cannot set. You control two flows with long lags on both, which is why the freeze always arrives after it was needed.

Your automation reported success. Nobody checked whether it ran.
A green status usually means the request was accepted, not that the work happened. Four questions to ask of any automation you already depend on.

Three bets that fail together are one bet
You sized each exposure carefully and separately. If they share a hidden dependency, you have one position three times the size you approved.

The AI advice you are reading was written for a company you do not run
Most AI advice assumes spare staff, a cheap meter, steady power and someone who can judge the output. Here is what breaks when a small business outside San Francisco follows…

The customers you lose to a price rise are not a random sample
A ten percent increase does not shave ten percent off the base evenly. It removes the accounts with the best alternatives first, and those are rarely your worst ones.
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
They were looking straight at the evidence that said no
Of 18 people who followed a wrong automated diagnosis, 11 had checked every parameter, including the ones that said no. Showing people more evidence is not the fix.
The vocabulary arrived and the theory did not
Someone is selling you a framework named after a book. Open the book and search for the framework. Often it is not in there.

Everyone has the wallet. Almost nobody pays a shop with it.
In Uganda, 67.7 percent of adults hold a mobile money account and 11.7 percent have ever paid a shop digitally. Between 2021 and 2024 that gap grew.

Overshoot has a signature you can read before the peak
Growth that levels off and growth that collapses look identical on the way up. One difference decides which one you are in, and you can check it now.

Your reply rate is counting the people who said no.
Three different numbers all get called the reply rate, and the gap between them is about fifteenfold. How to measure cold outreach properly, and when it pays at all.

Demand did not move. Your orders did.
End customers bought roughly the same amount all year. By the time that signal reached your factory it had become a boom and a crash.
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
Africa’s whole AI wave fits inside one ordinary year.
Six years of African AI funding comes to about a third of one year across all sectors. What the real size of the wave means for how founders here should…

You are negotiating against a number you did not choose
Every offer you receive arrives next to a reference point. Whoever set that reference has already done most of the work.

Raising pre-seed got harder. The money never left.
US pre-seed dollars held flat while the number of checks fell by a fifth. What that concentration means for how you price, pitch and plan a raise in 2026.

What you are buying when you refuse to decide
Waiting is not indecision when the thing you are waiting for arrives on a schedule. It becomes indecision the moment nothing new is coming.

Everything Works Except the Address: The Builder Stack From Uganda, Checked Tool by Tool
A founder in Austin can set up a company, bank account, payments and cloud credits in a week. I checked the same builder stack, tool by tool, from Kampala.
The decision that quietly removed your other options
The database, the first big customer, the co-founder split. None of them felt like a commitment at the time, and all of them are now load-bearing.
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
The Founders Stayed, the Companies Left: What 13 African Unicorns Say About Who Gets Funded
I used to say nearly every African unicorn has a founder who has been to the US. This week I counted all 13, and I was wrong in a useful…

You are grading them on a signal you cannot read
You can see the result. You cannot see the effort. Every performance judgement you make is an inference through noise, and most management systems pretend otherwise.
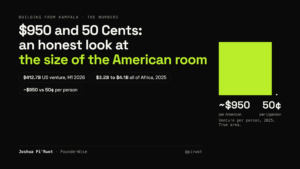
$950 and 50 Cents: An Honest Look at the Size of the American Room
US startups raised $412.7 billion in the first half of 2026. Ugandan startups raised $22 to $30 million in all of 2025. Here is an honest look at that gap.

The median tells you nothing about your portfolio
One position will decide the result and you cannot identify it in advance. That fact should change how many you hold, how you reserve, and what you promise.

The Rework Tax: What It Actually Costs to Build Software From Kampala
Ask a founder in Kampala what it costs to build here and you get a list of prices. The biggest line is missing from it: rework, the time you pay…

Nobody chose this price
The discount everyone offers, the trial length everyone matches, the salary band everyone pays. No meeting produced any of them, and no single company can leave.
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
What your market is teaching itself
At some point buyers stop evaluating you and start copying each other. Cascades are cheap to start, fragile to hold, and they carry almost no information.
The cost you are pushing onto someone else
Every process you skip lands on a customer, a teammate, or your next round. The bill arrives late, which is why founders keep signing it.

The commons you are quietly draining
The introduction network, the specialist talent pool, the investor's attention. Each is depleted by use and owned by nobody, which is exactly why it fails without warning.

Which account did they file your invoice under
Money is not fungible in practice. The same price is affordable from one budget and impossible from another, and you can often choose which.

They rejected free money. Here is why
A counterparty who walks away from a profitable offer is not being irrational. They are pricing the split, and the split is a term you can change.
Entry changes the answer for everyone already in
A crowded category is not evidence of demand. Positions cluster because clustering is individually rational, and the returns do not divide evenly.
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
We only ever measure the ones who made it.
Three published medians for the same population in the same year, and they differ by a factor of eight. Why that keeps happening, and the four numbers to track instead.
You won the round and that is the bad news
In a contest where everyone is valuing the same underlying thing, the winner is whoever estimated highest. Winning is evidence your estimate was wrong.
Building automation got cheap. Owning it did not.
Nine months of n8n security advisories, a benchmark collapse nobody mentions in the demo, and the three bills that arrive after the workflow is already running.
The ceiling on this relationship is pre-commitment
Against a stream of one-shot counterparties, the most you can ever earn is what you would get by committing publicly first. Cleverness inside the relationship cannot beat it.
Add the missing feedback. It is the cheapest thing that works
Someone in your company is making a decision and never sees its consequence. Connecting those two is usually a meeting invitation.
Your scorecard has no consistency ratio
You invented the weights. Nothing has ever checked whether your own stated priorities contradict each other, and they usually do.
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
There are no side effects
The consequence you did not plan for is not a property of the world. It is a report on the boundary you drew, and the boundary was yours.
Stop asking why. Split the accounts and read the difference
You will never see inside the algorithm, the buyer or the market. You do not need to. Vary one input and read the output.
Walk the term sheet to its end before you counter
A gain at step one that terminates below where you started is not a gain. And when the tree comes out symmetric, runway decides.
Start small on purpose, and say so
The first order is not a small version of the deal. It is the instrument you use to find out who you are dealing with.
Being right is not the same as being credited
Correct work does not carry its own recognition. Proof is a property of the work. Credit is the output of an institution, and it arrives late.
Your credibility is leaking right now
Reputation is not a balance you built and hold. It is a stock with an outflow, and the outflow runs whether or not you are watching.
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
They are not a bad hire, they are in a bad seat
If a different person in the same chair would behave the same way, you do not have a people problem. Replacing them resets nothing.
Copy the state, not the path
An open system reaches the same end from different starting points by different routes. Their sequence encodes conditions you do not have.
Your procrastination is about effort, not money
Present bias over money is modest. Over work it is large. That single split tells you where to put every deadline you set.
You have survived four failures and none of them mattered
Your record of absorbing shocks is evidence about small suppliers. It says nothing about the one you cannot replace.
You are not understaffed, you are short of variety
Count the distinct situations arriving. Count the distinct responses you have. If the second is smaller, hiring changes neither number.
The nudge you were sold does not work
Adjusted for publication bias, the average nudge effect is 0.04 with a confidence interval that includes zero. Change the payoff instead.
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
You cannot train this away
The failure in your operations is not a people problem. It has been tested against experience, incentives and competition, and it survived all three.
Trust is an inequality, not a virtue
Whether a counterparty keeps their word is decided by four numbers, and none of them is character.
The local grab must leave one future
Take the shiny hire, channel, or customer only if at least one still-acceptable future remains after the grab. One counterexample fails the rule.
They did one step, not four
Your investor, your buyer and your competitor are reasoning one move ahead. Your clever second-order signal is a cost you are paying alone.
The dashboard is a view. The log is the memory
Decide this week which records may be overwritten and which must only be appended. Investors reconstruct from a journal.
A good bet that can end you is not a good bet
Expected value is computed across parallel worlds. Your company lives in one, and it has an absorbing state at zero.
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
You Are Renting a Licence, and Rent Reprices
A sponsor-bank arrangement lets you launch without a licence. It also hands the sponsor the right to change the price the day their regulator moves.
The Tax Bill Nobody Modelled: What a Share Swap Does to You Personally
A flip is a taxable disposal in one country and a tax-free rollover in another. The founder who learns the difference after signing pays it out of their own pocket.
Stop searching for the exact tour
Connecting all sites cheaply is a tree. Visiting every city and returning is a tour. Name the class, then ship an approximation.
The Grant Is a Reporting Contract
Grant and challenge-fund capital is priced in founder-weeks of reporting, procurement and audit. Cost it before you apply, not after you win.
If the drawer cannot own the claim
The founder owns the number on the homepage, the pitch, and the monthly update. The contractor who made it pretty owns nothing, unless the brief put the claim in their…
Pro Rata Is the Term Your Best Investor Wants More Than Price
You will concede something to close the round. Concede the price and you lose a number once. Concede pro rata casually and you write your best investor a call option…
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →Do not pick the chart until you have the point
Name the one-sentence point before you pick a graphic for this week's investor update. If there is no point, do not graph.
Distributions to Paid-In Is the Number Your Investor Is Judged On
Your investor is graded on cash returned, not on paper marks, and that one fact explains the pressure you are getting and what to offer instead of what is being…
Court the broker, not the rolodex
Write two lists before you spend the next introduction: the loud rolodex, and the person who sits between a group you can reach and a group you cannot.
Cap Table Hygiene Is a Credibility Record
Undocumented promises, an unissued option pool, unsigned IP and unvested founders are read as bad news the day a term sheet lands. Execute the five documents this month, while each…
Change the offer without breaking old counterparties
Schemas are the API of the relationship. Additive first. A break needs both shapes live, a dated close, and one writer who owns the cut.
Your TAM Slide Is Being Discounted, and You Can Tell By How Much
A top-down market size lifted from a consultancy PDF is priced near zero by an investor who cannot check it. Build the number a stranger can rebuild, and the gap…
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
Tranching Buys the Investor an Option on Your Milestone
A milestone tranche converts your unverifiable forecast into an option the investor can buy. Name the trigger yourself, and price it, before they draft it for you.
Secondaries Are the Liquidity Event You Should Negotiate For
The likeliest cash your cap table ever produces is a partial sale inside a later round, and it is a term you negotiate on the way in while you still…
A lower bound is permission to stop
If every candidate still needs the same three reference calls, remaining spend cannot buy a faster loop. Name the unit the tool deletes, or do not pay.
Every objection is a translation problem
An objection is not a rejection.
Revenue-Based Finance Prices Your Volatility, Not Your Failure
A revenue-share facility forgives a bad month and even a bad year. What it cannot carry is an unpredictable one, so the instrument fits a smooth collection cycle and quietly…
Float Is Someone Else’s Balance Sheet Until It Is Not
The customer money you hold sits on a partner's books as their asset and your liability, and the morning their problem becomes yours, no assurance unfreezes it.
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
A Valuation Cap Is a Promise About a Round You Have Not Raised
The cap you celebrate today is a strike price on a round you have not raised. Set it above what you can clear, and the good news reprices into a…
The two dashboards will disagree
Two readers of one stream will disagree while writes continue. Bound the lag, or serialize the join.
The Machine Has No Taste
Which affiliate and content loops may run unattended, and which must stop for a human. Variety, reputation, and ruin, applied to a thirteen recipe automation playbook.
You do not need a network. You need one person.
The advice you have been given is to build a network.
Same payment id, one debit
A second tap or a webhook retry can debit twice. Deduplicate on a stable id. Exactly-once does not travel across HTTP or a bank.
An Audit Buys You a Discount You Can Compute
Treat the audit as a purchase of verification, then run the return on it: the discount an investor drops when your numbers stop needing to be trusted is a number…
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
Your Most Likely Acquirer Is a Bank, a Telco or a Regional PE Firm
The realistic African buyer set is small, strategic and slow. It buys licences, distribution and books, not growth. That changes what you build three years before you sell.
The Personal Guarantee Moves the Risk From the Company to Your House
A director's guarantee reattaches the downside your incorporation removed, so cap it, carve it to acts you control, and put an institution's balance sheet where your house is being asked…
The twentieth time you solve the same problem, stop quoting it
You have solved the same problem for twenty clients. Each time you scoped it fresh, quoted it fresh, and negotiated it fresh.
The Instrument Decides What Happens When You Miss
A term sheet is not a price. It is a set of instructions for the bad states, and the instructions do the real deciding.
The Flip Is a Verification Purchase, and It Has a Price List
Reincorporating into Delaware or Mauritius buys your investor a legal system they already know how to check. The only live question is when to pay for it.
The Data Room Should Already Exist
A data room assembled during a raise dates itself in a suspicious cluster. One kept an hour a month dates itself honestly, and the date is the part a liar…
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
Ten, fifteen, or twenty percent: what each band actually costs you to claim
You have found the number. The work you are proposing is worth about fifty thousand a year to the buyer.
Nobody Exercises Options in a Market With No Exits
An option pays only when there is a sale to exercise into. In a market of two dozen exits a year, most option grants are a currency the holder can…
Nobody funds a system they cannot see
You built the thing. It works. The investor said no.
Debt Was the Bigger Half, and the Advice Was All About the Other One
Debt is 41% of the capital African startups raise, and it is growing faster than equity. It is the larger of the two pools most founders can actually reach, and…
One Fraud Re-Prices the Whole Cohort
When a founder in your category is caught lying, the market raises the checking bill for everyone who looks like them, and mails part of it to you.
Money You Cannot Repatriate Is Not Money You Can Spend
A company can be profitable in local currency and still have that profit trapped, because repatriability is a separate property of the cash, with its own queue, its own price,…
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
Fund Size Tells You What Outcome Your Investor Needs
A 0m fund and a 00m fund need different exits from the same company. Read the fund and you know what your investor needs before the first meeting.
Agent Networks Are Labour, Not Software
Founders price an agent network like software that scales for nearly free. It is a labour force with recruitment, training, churn and management costs, and that changes both the unit…
Your Best Customer Is Also Your Lender
In African B2B and B2G, the biggest contract you sign is often the biggest loan you make. Price the term, or the term prices you.
The Monthly Update Is the Cheapest Credibility Instrument
A dated note you send every month, especially the bad ones, builds a track record a future investor cannot manufacture, and that record is what decides the next round.
Read the circular before it reaches your model
In African markets a regulator rewrites your unit economics faster than any competitor can. Reading primary sources on a schedule is the cheapest edge you are not using.
Liquidation Preference Below the Line: The Term That Decides Who Gets Paid
The valuation decides how the story reads. The preference stack decides how the money moves. In a market of small exits, only one of those is your outcome.
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
Domicile Is a Signal to Two Audiences at Once
Where you incorporate is read by a foreign fund and a local regulator in opposite directions. Pick for the counterparty you cannot afford to lose.
Size the Market From the Bottom, One Verifiable Row at a Time
When no top-down TAM survives diligence, the credible market size is the one you build from counts a stranger can check.
A Lender Checks You Faster Than an Investor. That Is the Whole Point.
The fastest capital is not the cheapest. It is the one whose checking machine already fits the records you hold.
Your CAC Did Not Break. Someone Else Raised.
Acquisition cost is a price set in an auction you do not run, and the bidder who moved it never appears on your dashboard.
You Are Selling FX Certainty for Free
A fixed price in a moving currency is an option you wrote for your customer. It has a market price, and you charged nothing for it.
The Funded Competitor Taxes the Company That Stays Disciplined
A rival's round is a price change in your market, and the only decision that pays is which fronts you concede on purpose.
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
Money Does Not Buy an Input That Does Not Respond to Money
A raise relieves every constraint that carries a price. Find out whether yours does before you sign.
Too Much to Know: They Complained About Information Overload 2,000 Years Before Your Inbox
Every overload panic on record was answered the same two ways. Knowing which two tells you exactly where to spend the next hour.
7±2 Is a Myth (Sort Of): What Miller Really Said About Working Memory
Miller measured two limits, and neither one is the rule you are quoting. Build for four chunks, then spend everything else on making each chunk bigger.
Decision Quality Is a Scheduling Variable: Sleep Pressure, Circadian Phase, Block Length
Three measurable inputs govern how well you decide across a working day, and they imply a different calendar from the one most founders run.
Creative Desperation: The Insights That Only Show Up When You’re Cornered
A corner does not raise your intelligence. It cuts the price of dropping the assumption that was capping your options.
Why ‘Why Now’ Is the Most Underrated Slide
It is the only slide that puts an expiry date on the opportunity, and most founders fill it with trends.
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
Warm Introductions: How They Actually Get Made
An intro is a loan against someone else's reputation, and the terms are set long before you ask for it.
The Unit-Economics Conversation Founders Avoid
Volume multiplies whatever sign your contribution margin already carries, and somebody else is paying for the sign you have now.
The ‘This Doesn’t Make Sense’ Reflex: Turning Dashboard Anomalies Into Your Next Product
The number you cannot explain is a customer doing a job you never built for, and the story you invent to explain it is how you lose them.
The Premortem: Run Your Startup’s Funeral Before You Launch
The technique works because certainty changes what the mind is allowed to retrieve, and what the room is allowed to say.
The One-Page Memo That Outperforms the Deck
A deck is a visual aid for a narrator, and the room where your round gets decided has no narrator.
The Objection Is the Offer
A no with a condition attached is a specification someone else wrote for you. A no without one is an exit, and building against it wastes a quarter.
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
Speed vs. Quality: A Framework for Knowing Which One This Decision Needs
Two numbers set the dial: what it costs to correct the call once it is wrong, and how much error the extra time actually removes.
Retention Is the Metric That Survives Diligence
Every other number on your dashboard is a stock somebody else gets to re-count. Retention is a rate inside a closed cohort, which is why it holds its shape.
Informal Proof Is Still Proof
The evidence of your business already exists. It sits in WhatsApp threads, till books and mobile money statements, in a format no investor can price.
How to Read Your Own Business the Way an Investor Does
An investor prices the class before they read the company, and the checkable part before the true part. Run that order on yourself first.
Founder-Market Fit Is Evidence a Stranger Can Check
Dated calls, access nobody else can buy, and contact recent enough to still be true. That is the whole of it.
Default Alive Is a Question Every Founder Should Answer Monthly
The cheapest fix for a default-dead company takes about three months to run, so a quarterly review finds the problem after the window to solve it has closed.
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
Decisions, Not Feeds: Building a Personal Information Diet
Your inputs are a portfolio. Price every one of them by the decision it can change, then cancel the rest.
Cynefin for Founders: Matching Your Decision Style to the Mess in Front of You
Every problem has a class, and the class picks the method. Get the class wrong and effort stops helping.
Complicated or Complex: A Field Guide to the Problem in Your Hands
A complicated problem has an answer an expert can hand you. A complex one only releases its answer to a probe you can afford to lose.
The First Overload Panic: What the 16th-Century Firehose Teaches Founders About Decisions, Not Feeds
When Gutenberg's press flooded Europe with more books than anyone could read, the scholars who survived the deluge did so not by consuming more—but by deciding better.
Confirmation Bias in Product Discovery: How Founders Interview Customers Into Lying
The customer interview is product discovery's most trusted tool — and its most dangerous, because founders routinely design conversations that produce the answers they already believe.
The Man Who Saw It Coming: Herbert Simon and the Sentence That Explains the Attention Economy
In 1971, a Nobel laureate wrote one sentence that predicted the defining constraint of modern business — and most founders are still misreading it.
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
Pre-Commitment: Deciding Now So Your Tired, Emotional Future Self Doesn’t Have To
The science of locking in your best judgment before fatigue, pressure, and distraction corrupt it — and why the most effective founders treat pre-commitment as an operating system, not a…
The DIKW Pyramid, Explained: Why Founders Confuse Data, Information, Knowledge, and Wisdom Daily
Most founders drown in data and call it strategy — the DIKW pyramid reveals exactly where the confusion happens and how to climb toward decisions that actually compound.
The Cognitive Biases That Quietly Run Your Cap-Table Decisions
Five well-documented biases — anchoring, loss aversion, overconfidence, confirmation bias, and the sunk-cost fallacy — distort how founders structure equity, negotiate terms, and decide when to walk away; recognising them…
Vannevar Bush Dreamed the Internet in 1945. What Founders Should Actually Take From It.
Bush's memex wasn't a technology prediction — it was a decision-making manifesto, and eighty years later most founders are still ignoring the core argument.
Decisions Under Ambiguity: How to Act When the Data Doesn’t Exist Yet
Founders don't lack courage—they lack a disciplined vocabulary for the specific kind of uncertainty that precedes all markets, all data, and all proof.
Sunk-Cost Fallacy: The Founder’s Most Expensive Emotion
The bias that keeps founders pouring resources into failing ventures is not a logic error — it is an identity crisis dressed up as strategy.
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
The Poverty of Attention: A Plain-English Guide to Simon’s Economics of Focus
Herbert Simon proved in 1971 that information abundance creates a scarcity of attention — and every founder who has ever lost a morning to a feed instead of a decision…
It’s Not Information Overload. It’s Decision Architecture Failure.
Clay Shirky was right that the feed was never the problem — but the deeper crisis for founders is not filtering inputs, it's structuring the decisions those inputs are supposed…
Cognitive Load Theory for Operators: The Three Kinds of Mental Load Your Dashboards Create
Most dashboards are built to display data — but the cognitive science of how operators actually make decisions demands something far more deliberate.
Before the Algorithm There Was the Index: How the Card Catalog Solved a ‘New’ Problem
The information-overload crisis that founders blame on social feeds was solved once before—in wood and paper—and the design logic still works.
Proof, Not Promises: Why the Next Era of African Venture Runs on Verified Traction
Investors have quietly stopped believing founder-reported numbers — and the replacement for belief is not more diligence, it is infrastructure. Here is the case for verified traction, and the honest…
The Three Doors to Insight: How Gary Klein’s Triple Path Model Should Reshape the Way Founders Make Decisions
Insights are not accidents — they arrive through three distinct cognitive pathways, and founders who learn to work each one deliberately will out-decide any competitor who is merely consuming information.
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
Who Really Invented DIKW? From a T.S. Eliot Poem to Ackoff — and What It Means for Your Decisions
The Data–Information–Knowledge–Wisdom hierarchy has a contested, 90-year genealogy — and understanding it reveals why most founders are optimising the wrong layer.
Decision Fatigue Is Real (Maybe): What the Ego-Depletion Replication Crisis Really Proved
The science behind decision fatigue is far messier than the productivity industry admits — and that ambiguity is precisely what founders should act on.
The Founder’s Filter Stack: A Hierarchy for What to Ignore, Skim, Read, and Act On
In a world where attention is the scarcest resource, the founders who win are not those who consume the most information—they are those who have built a deliberate system for…
The Grey T-Shirt Won’t Save You: The Shaky Science of Decision Fatigue
The willpower-as-fuel theory that launched a thousand morning routines has largely collapsed under scientific scrutiny — here is what founders should do instead.
Radical Responsibility: The Operating Principle of High-Agency Founders
Owning every outcome — not just the wins — is the single trait that separates founders who scale from those who stall.
The Identity Shift: Thinking Like an Owner, Not an Employee
The move from employee to founder is not a career change—it is a cognitive rewiring that restructures every decision a founder makes, from resource allocation to risk tolerance to the…
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
The Bias for Action: Why Speed Compounds for Founders
Decision velocity is not a personality trait—it is a compounding operating system that separates founders who build durable advantages from those who wait for certainty that never arrives.
Reversible vs. Irreversible: A Founder’s Decision-Speed Framework
Most founders over-deliberate cheap choices and under-deliberate expensive ones — Bezos's one-way/two-way door framework fixes both failure modes simultaneously.
The Audacity Gap: Why Founders Systematically Underask
Operators who underask on raises, pricing, and scope don't just leave money on the table—they set a ceiling on everything that follows.
The Disagreeableness Premium: Why the Best Founders Push Back
Independent-mindedness and a willingness to hold unpopular positions are not personality flaws in founders — they are measurable predictors of venture success.
Do Things That Don’t Scale: The Unscalable Advantage
Early manual effort is not a workaround — it is the mechanism by which durable competitive moats are built, and knowing when to stop is the discipline that separates founders…
Default Aggressive: Calibrating Risk Appetite Under Uncertainty
When the payoff structure is nonlinear, the correct default is not caution — it is disciplined aggression, bounded by survivability.
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
The Cost of Inaction: Why Waiting Is the Riskiest Move a Founder Can Make
Inaction feels safe but carries a measurable, compounding price—and for capable operators, it is the most common path to irrelevance.
Tempo Over Strategy: Why Operating Speed Beats a Perfect Plan
The founder who cycles through reality faster than rivals compounds an advantage that no amount of strategic planning can replicate.
The Cereal Box Theory of Fundraising
Cereal box theory of fundraising: how Airbnb's Obama O's story reveals the principle that scrappy, unscalable action beats waiting for the right funding channel
Grit Is Overrated: The Meta-Analysis That Proves It
Grit is overrated: Credé et al.'s 88-study meta-analysis shows grit weakly predicts performance (r≈.18) and duplicates conscientiousness. Here's what actually d
Manufacturing Luck: Naval Ravikant’s Luck Surface Area
Luck surface area explained: Naval Ravikant's four kinds of luck and a tactical checklist for founders to engineer more serendipity this quarter.
Start Before You’re Ready
Start before you're ready: why most credential gates are self-imposed and how decisive action, not preparation, builds lasting founder competence.
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
Permissionless: The Operating System of Every Founder Who Shipped
Permissionless action is the operating system of every founder who ships. Learn why waiting for permission is the default failure mode of talented people.
Agency vs. Luck: An Honest Accounting
Agency vs. luck in startups: research-backed framework for founders to separate what they controlled from what fortune handed them — and build better systems.
100 Nos and a $40B Company: The Melanie Perkins Playbook
Melanie Perkins faced 100+ investor rejections before building Canva into a $40B company. Reverse-engineer her playbook on reframing rejection, affordable loss,
The Agency Gap: Why Identical Resumes Produce Different Lives
Agency gap: why locus of control and self-efficacy — not talent or credentials — compound into wildly different career and founder outcomes over time.
Nobody Is Coming to Save You
Nobody is coming to save your startup. Grounded in Rotter's locus of control and self-authorship theory, here's why founder agency is your only durable edge.
Self-Efficacy Is Not Confidence
Self-efficacy vs confidence: how Bandura's four sources — mastery, vicarious experience, persuasion, physiological state — help founders build execution belief
One sharp call a day. Zero noise.
The decision brief for founders building in East Africa. Free, every weekday.
Get the Brief →
You Can Just Do Things: An Honest History of the Phrase
"You can just do things" — tracing the founder-agency ethos from Steve Jobs 1994 to the 2024 meme, separating load-bearing truth from tech-elite entitlement.
The Jail-Cell Test: How to Measure High Agency
High agency defined: use George Mack's jail-cell test to measure clear thinking, bias to action, and productive disagreeability in yourself and your team.
The Museum of Passion Projects
Founder agency starts with one insight: the world is built, not given. John Collison's "museum of passion projects" reframed as a call to decisive action.
‘You Can Just Do Things’ Is Survivorship Bias Wearing a Motivational Hoodie
Survivorship bias distorts the 'you can just do things' founder narrative. Here's what the data on mobility, failure rates, and capital access actually says — a
Ask Forgiveness, Not Permission: A Doctrine for High-Agency Operators
Ask forgiveness not permission: the practical framework for high-agency founders — when to act without sign-off and when caution is non-negotiable.
Why Capital Platforms Are Critical for Developing Economies
Capital platforms in developing economies: how software-mediated trust closes information, trust, and distribution asymmetries to unlock the $5.7T SME finance g
See your business the way an investor reads it.
12 questions, about 3 minutes. Your score out of 100 and the three gaps in the way of a yes.
Take the free audit →
AI-Verified Diligence: Cutting Decision Time From Weeks to Hours
AI-verified diligence compresses document review, fraud detection, and risk scoring from weeks to hours—here is what it reliably catches and where human judgmen
The History of Credibility: From Clay Tablets to Cryptographic Proof
From Mesopotamian clay tablets to W3C Verifiable Credentials, trace how humanity has scaled trust across strangers — and what it means for cross-border startup
Why Physical Verification Still Works in Developing Economies
Physical verification remains a high-signal trust tool in developing economies. Learn why hybrid physical-cryptographic systems beat digital-only KYC in thin-re
How a Deal Actually Closes: Transaction Infrastructure for Cross-Border Investing
How transaction infrastructure—SAFE notes, e-signature, escrow, and KYC verification—unlocks cross-border startup investing. Evidence-led analysis for founders
Alternative Credit Data: The New Underwriting Logic for Frontier Startups
How alternative credit data—mobile money, payments, supplier records, traction proofs—underwrites frontier startups where credit bureaus are thin. Global resear
The Six Gaps Holding Back Founders in Developing Countries
Six structural gaps keep frontier founders under-capitalised. Discover which is the binding constraint and how verification infrastructure attacks several at on
Your industry. Your market. Your brief.
The Dispatch, tuned to your exact segment and delivered weekly.
See Tuned Dispatch →
How Trust Develops in Developing Economies — And Why It Matters for Capital
How trust develops in developing economies, why capital flows through personal networks in low-trust markets, and how verification infrastructure substitutes fo
KYC-Verified Founders: The Trust Layer Every Marketplace Needs
KYC-verified founders: why a 3-step identity check (government ID, proof of address, facial liveness) plus human review is the optimal trust layer for cross-bor
No articles match those filters yet.
Lock in your calls.
You’ve marked 0 of 5. Now choose how often you want the signals.
Step 1 · Pick your cadence
Step 2 · Where to send it
Get it on WhatsApp insteadFor teams, syndicates & programs
- Everyone on the same signal
- Admin + shared watch-list
- One invoice · ~25% off solo
- MVP Studio and GTM Studio for every founder
- Your logo, your cohort
- A funder report on what each founder did
Decisions, not feeds. · Curated by Joshua Pi’Rwot · FounderWise · Free Audit · Store · parent of Business Growth Accelerator